All Categories
Featured

Mastering the British Enterprise Expansion in 2026
Table of Contents
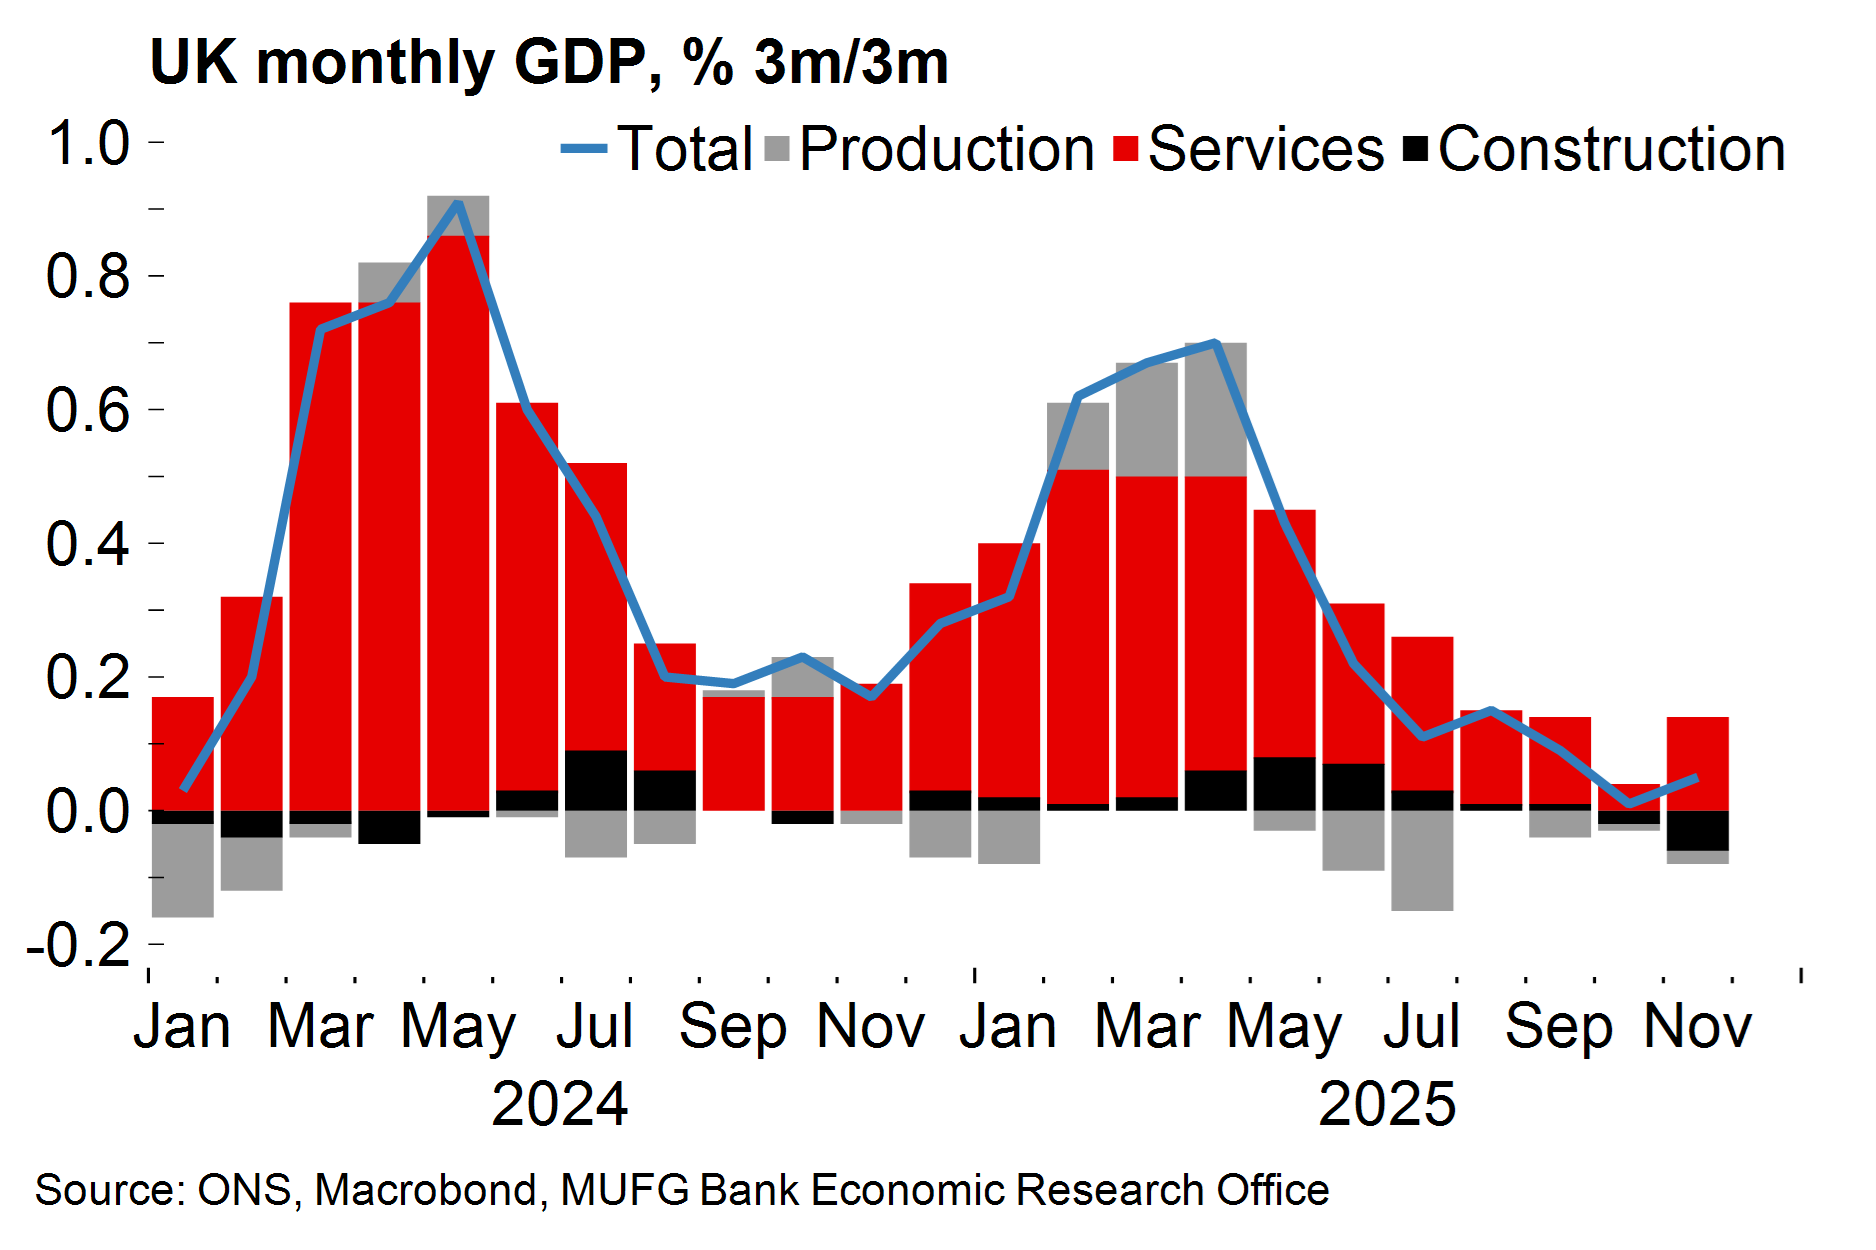
"Big ticket purchases were back on the table with car sales especially greater, people were currently reserving their summertime holidays, and accounting professionals and accountants saw a spike in workload as businesses gotten ready for the huge modification of Making Tax Digital which went live at the start of April." Hewson included the bounce back from last year's cyber-attack on Jaguar Land Rover was continuing to power the production sector as the supply chain raced to make the most of suppressed demand.
"This will have just been exacerbated by the scenario in the Middle East, which has modified the anticipated path of interest rates." Barret Kupelian, primary economist at PwC, added: "Had the UK economy begun to turn a corner after the Autumn Statement and before the newest advancements in the Middle East? Today's information recommends it had.
Output grew by 0.5% in the three months to February, with both production and services expanding together. "More notably, this was development powered by the personal sector instead of the public sector-dominated parts of the economy that had propped up much of the post-2023 picture. That suggested the recovery was ending up being more comprehensive and more durable.
Our summer outlook probably isn't as bad as England's opportunities of winning the World Cup this summer, but it still doesn't produce the most pleasant reading. The Iran dispute has pressed up our inflation projection, weighing on growth and the labour market. Domestic political uncertainty, including yet another change in Prime Minister, adds more headwinds through greater loaning expenses and gilt yield pressure.
Optimizing UK Talent Acquisition in 2026The threats to that outlook are bigger than usual and heavily depending on how the scenario in the Middle East develops. However the economy has actually grown at approximately 1.2% through 2 rough years, and the early signs recommend that strength will hold. Growth will be slower than in 2015 and with inflation on its method back up the UK is in for another batch of 'stagflation'.
Investment Banking Developments Impact British Mid-Market Strategy
Dangers loom big, the war in the Middle East will decide whether the UK economy goes into economic crisis. Partner In between the Iran conflict and yet another tussle for no. 10, this summertime's outlook carries a much larger health caution than normal. Our base case is slower development and increasing inflation, however not recession.
The UK is especially exposed offered its reliance on gas for electrical power prices, which is why the International Monetary Fund (IMF) has modified its UK inflation and growth forecasts more greatly than any other industrialized economy. Inflation briefly dipped below 3% for the very first time because early 2025, but the reprieve will be brief.
A weaker labour market and softer need should avoid a repeat of 2022's double-digit spike, restricting second-round effects. Our base case is inflation averaging 3.1% in 2026, peaking around 3.5%, before reducing to 2.5% in 2027, though threats loom big if the Strait of Hormuz remains closed. The UK labour market was already softening before the current energy shock, with joblessness increasing to 5.0% and jobs at their least expensive considering that the pandemic.
Optimizing UK Talent Acquisition in 2026Companies are not yet shedding personnel, but reluctance to employ is expanding the gap in between job growth and population growth. Higher energy expenses will intensify the pressure, and we anticipate unemployment to peak at 5.3% by year end. With wage development slowing to around 3.75% and inflation heading towards 3.5%, genuine pay looks set to be stagnant another hard year for living requirements.
3 aspects restrict the case for walkings: the energy shock is smaller sized than in 2022, rates are already at a limiting level, and a weaker economy minimizes the threat of second-round inflation effects. That stated, rate increases can not be eliminated if energy prices rise even more. Gilt yields are most likely to remain raised regardless, driven by the UK's inflation sensitivity and political unpredictability around a prospective modification of Prime Minister, keeping borrowing costs high throughout the economy even if the policy rate stays on hold.
Key Enterprise Tips for British Mid-Market Executives
The UK is especially exposed given its reliance on gas for electrical power rates, which is why the International Monetary Fund (IMF) has actually modified its UK inflation and growth projections more sharply than any other developed economy. Inflation briefly dipped below 3% for the first time because early 2025, however the reprieve will be temporary.
A weaker labour market and softer demand must avoid a repeat of 2022's double-digit spike, restricting second-round effects. Our base case is inflation averaging 3.1% in 2026, peaking around 3.5%, before alleviating to 2.5% in 2027, though dangers loom large if the Strait of Hormuz remains closed. The UK labour market was already softening before the most current energy shock, with joblessness increasing to 5.0% and jobs at their lowest considering that the pandemic.
Companies are not yet shedding staff, but unwillingness to employ is widening the gap in between job development and population growth. Greater energy costs will compound the pressure, and we anticipate joblessness to peak at 5.3% by year end. With wage development slowing to around 3.75% and inflation heading towards 3.5%, real pay looks set to be stagnant another tough year for living requirements.
Three aspects restrict the case for walkings: the energy shock is smaller sized than in 2022, rates are currently at a restrictive level, and a weaker economy reduces the threat of second-round inflation results. That said, rate rises can not be eliminated if energy rates rise further. Gilt yields are likely to remain raised regardless, driven by the UK's inflation level of sensitivity and political unpredictability around a prospective modification of Prime Minister, keeping loaning expenses high across the economy even if the policy rate stays on hold.

Latest Posts
How Digital Tools Redefine Global Business
How Global Trade Shifts Impact UK Firms
How Digital Transformation Redefines Mid-Market Efficiency